Clarity before you shop
Explore your budget, down payment, and loan options early so you can focus your search with a clearer understanding of the numbers.
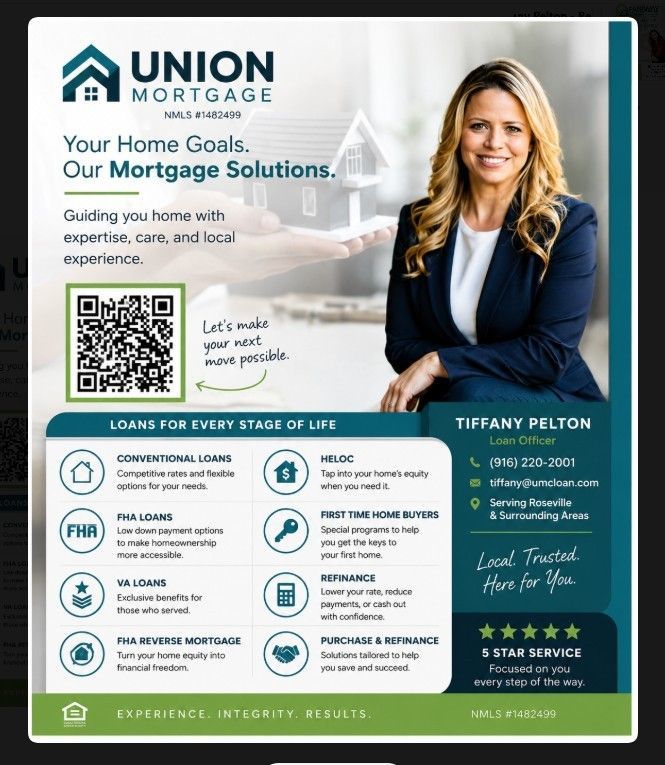
A great home search starts with a clear financing plan. Tiffany brings the mortgage perspective to the JRhomes of CA team, helping you connect the home you want with a payment and loan strategy that fit your goals.
Explore your budget, down payment, and loan options early so you can focus your search with a clearer understanding of the numbers.
Tiffany helps you understand financing milestones and documentation, while your JRhomes of CA agent guides the home search and purchase process.
When your needs change, Tiffany is a resource for comparing refinance and home equity options, including their costs and tradeoffs.
A starting point for buyers and homeowners in Roseville, Rocklin, and communities across Placer County.
Information reviewed September 11, 2026.
Ask Tiffany about your situation →Not always. Some loan programs allow smaller down payments, depending on your qualifications and the property. A smaller down payment can mean mortgage insurance or a higher overall borrowing cost. Tiffany can help you compare the upfront cash and monthly payment for the options available to you.
Start with the property’s location and your household eligibility. Placer County’s first-time homebuyer program serves unincorporated areas and currently says it is not accepting new applications; an interest list is available. CalHFA’s MyHome program is another resource for eligible first-time buyers through approved lenders. It is a repayable assistance loan, with program, income, and education requirements. Availability and lender participation must be confirmed.
The 2026 application window closed on March 16, 2026. Check CalHFA for future updates rather than assuming a new application can be submitted now. Dream For All is a shared-appreciation loan, so repayment can include a share of the home’s increase in value. Ask about other available options while you plan your purchase.
For a one-unit property, the 2026 conforming loan limit is $832,750. This is a loan amount limit, not a maximum home price. A loan above that amount may require jumbo financing. Two- to four-unit properties have different limits, and your approval still depends on the lender’s requirements.
Plan for principal and interest, property taxes, homeowners insurance, any mortgage insurance, and HOA dues where applicable. Also leave room for maintenance and utilities. Your Loan Estimate separates projected payments, closing costs, and estimated cash to close. Ask Tiffany to walk through these numbers for the specific home you are considering.
Start with an actual loan quote and your goal: a lower payment, a shorter term, or a different loan structure. Compare closing costs with potential savings and how long you expect to keep the loan. A lower payment does not always mean a lower total cost, especially if you extend repayment. Tiffany can help you compare scenarios without relying on a prediction about future rates.
A HELOC may let you borrow against equity while keeping your existing first mortgage. A cash-out refinance replaces that mortgage with a new loan. Compare the combined payments, fees, and repayment terms. HELOC rates are commonly variable, so payments can change; your home secures the debt.
Insurance availability and premiums deserve an early check, especially for foothill properties. Lenders generally require homeowners insurance, and its cost affects your budget. If standard coverage is unavailable, ask a licensed insurance broker about the California FAIR Plan and any additional coverage needed. FAIR Plan policies provide limited coverage and are not equivalent to a standard comprehensive homeowners policy.
Gather recent pay stubs, bank statements, tax returns, employment information, and details about existing debts. If you are refinancing, include your current mortgage statement. Your lender may request more based on your situation. An early conversation can clarify next steps; preapproval is conditional and does not guarantee final loan approval.
General information, not a loan commitment. Qualification, terms, program availability, and insurance requirements vary. Confirm current details with the lender or program administrator.